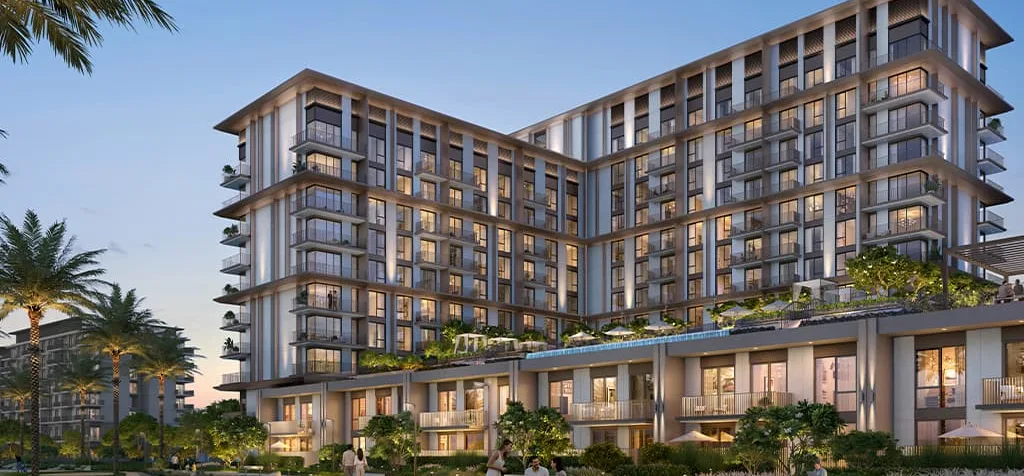
Emaar South
Golf Trails
On the edge of the championship golf course, five minutes from Al Maktoum International. A long handover and a low entry point for an Emaar address.
£257,000Prices from
£26kDeposit from
Q4 2030Completion
Home/News, articles and guides/Market Data
Market Data
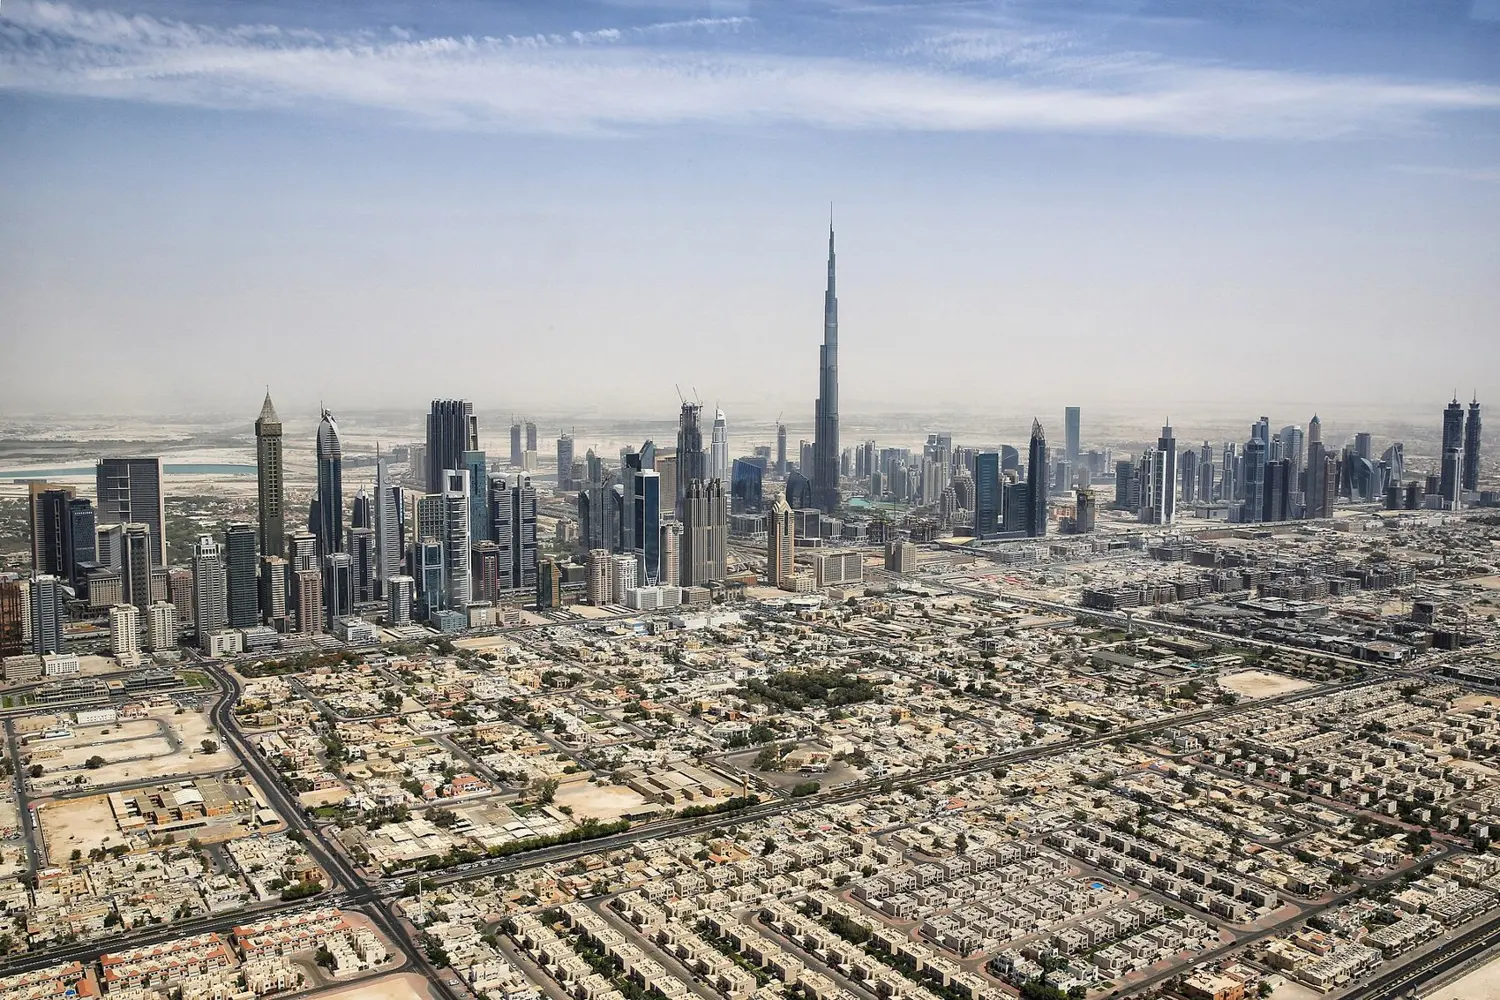
The Dubai property market has moved from a record run into a correction. Residential sales in the third quarter of 2026 were about AED 72.6 billion across roughly 34,000 transactions, down 47 per cent by value and 38 per cent by number on the record third quarter of 2025. Prices are 1.7 to 3 per cent below a year ago on the main indices, off plan still takes 72 per cent of deals, new lease rents have come off their peak, and about 55,600 homes are due to complete this year. It is a buyer's market for the first time since 2020, and a selective one.
| Measure | Q3 2026 | Change on Q3 2025 | Source |
|---|---|---|---|
| Residential sales value | AED 72.6bn (£14.9bn) | down 47% | Cavendish Maxwell |
| Residential transactions | about 34,000 | down 38% | Cavendish Maxwell |
| All property sales, DLD register | about AED 93bn, 37,000 deals | down 45% by value | W Capital, Harbor |
| Off plan share of transactions | 72% | Q2 2026: 76% (Betterhomes) | Cavendish Maxwell |
| January to September sales | 112,580 deals, AED 292bn | down 23% and 27% | Cavendish Maxwell |
| Average price, August | AED 1,636 per sq ft | down 1.7% | Cavendish Maxwell |
| ValuStrat price index, August | down 3.1% | ValuStrat | |
| Gross yield, Q1 2026 | 7.2% apartments, 5.0% villas | Cavendish Maxwell | |
| Completions due in 2026 | about 55,600 homes | highest since 2008 | Cushman and Wakefield Core |
September alone saw about 10,100 sales worth AED 21.3 billion, down 47 per cent and 51 per cent on September 2025, with 69 per cent of them off plan. Quarter on quarter the picture is calmer: transaction numbers were within 2 per cent of the second quarter and value about 15 per cent lower, so the market has found a level rather than falling further each month.
The comparison is against the biggest quarter the city has ever had. The third quarter of 2025 recorded about AED 169 billion of sales across 59,000 deals, the peak of a run in which annual volumes went from 84,000 in 2021 to more than 200,000 in 2025. Measured against 2023 or 2024, 2026 volumes are ordinary rather than weak.
Three things took the top off. Regional tension in the summer paused some overseas buyers for a few weeks and made others more selective. Developers launched fewer projects in the quarter, and launches are what drive off plan volumes in Dubai, since most deals are signed in the first days of a release. And prices had doubled in the districts most investors buy in, so the easy arithmetic of 2022 and 2023, when almost anything bought off plan was worth more at handover, stopped working. Buyers now ask what a building will rent for, and sales have slowed to the pace at which that question gets a good answer.
After roughly 20 per cent growth in 2022, 14 per cent in 2023, 12 per cent in 2024 and close to 20 per cent in 2025, prices turned in the spring of 2026. ValuStrat recorded its first monthly fall in March, Cavendish Maxwell the first annual fall in August at 1.7 per cent, and industry estimates compiled by S&P Global put the decline from the end of 2025 at between 5 and 15 per cent depending on the segment. Villas have held better than apartments, and prime better than mid market. My prices guide has the price per square foot by area and what each budget buys.
Off plan took 72 per cent of transactions and 65 per cent of value in the quarter, down from 76 per cent in the spring. The more interesting number is on the other side: ready apartment sales rose 16.4 per cent quarter on quarter to AED 12.8 billion across 7,825 deals, and in September ready sales outweighed off plan by value for the first time in two years. Some of that is completed stock from the 2022 and 2023 launches reaching the market, and some is buyers choosing a home they can see and rent today over a launch three years out. For an off plan buyer the lesson is to look hard at the off plan or completed question and at the developer's record of delivering on time.
Rents rose about 10 per cent a year through 2024 and 2025 and are now flat to lower. Cavendish Maxwell had citywide rents down 1.1 per cent in the three months to May 2026, with villas and townhouses off 2.1 per cent, while rents on new leases in the mid market apartment districts have fallen further as completions arrive. Renewals, which RERA's rent index caps, have barely moved, so a landlord with a sitting tenant has felt little of it.
Gross yields remain the reason to own here. Cavendish Maxwell put the first quarter at 7.2 per cent gross for apartments and 5.0 per cent gross for villas and townhouses, against 3 to 5 per cent gross in many established Western markets. JVC runs at 7.4 per cent gross, Business Bay 6.6 per cent, Dubai Creek Harbour 5.9 per cent and Dubai Hills 4.4 per cent on current asking prices and rents. Net of service charges, which are higher than in many markets and run AED 12 to 30 per square foot a year, take roughly a fifth off those figures. My letting guide covers the costs line by line.
This is the number to watch. Cushman and Wakefield Core expects about 55,600 homes to complete in 2026, the most since 2008, and more than 60,000 in 2027. Moody's puts deliveries at around 180,000 homes across 2026 to 2028, concentrated in mid market apartments, and S&P expects the residential stock, especially apartments, to grow about 20 per cent in two years. Developers have almost 525,000 units planned through 2030, of which about 186,000 are past 20 per cent construction.
Two caveats. Dubai never delivers what it schedules: Cavendish Maxwell found that only 42 per cent of the completions projected for the first quarter of 2026 actually arrived, and the slippage grows when sales slow. And the population is still rising by around 150,000 a year, which absorbs a large share of what does complete. The risk is not citywide. It sits in the mid market apartment districts with the most towers under construction, which is where the steepest rent falls on new leases are already showing.
By number of homes sold in September 2026, the busiest areas were Dubai South with 842, Jumeirah Village Circle with 784 and Majan with 523, all mid market and all driven by launches. By value the established districts led: Dubai Marina, Palm Jumeirah, Downtown, Business Bay and Dubai Hills Estate. The biggest selling single projects in the month were Azizi Venice in Dubai South, Valia and Binghatti Skyterraces. For an overseas buyer the sensible ground is usually between the two: a masterplan from a major developer, close to a metro line that exists or is funded, priced below the prime districts but above the volume launches. The projects on my featured list are chosen on that basis.
Mortgage lending is growing even as cash sales fall. There were about 10,800 mortgage transactions worth AED 23.1 billion in the first quarter of 2026, up 16 per cent by number on a year earlier. The UAE central bank follows the US Federal Reserve, so rates have eased from their 2024 peak, and overseas buyers can borrow up to 50 per cent on off plan and 50 to 60 per cent on completed property. My mortgage guide covers who lends and on what terms, and most buyers on this site use the developer's payment plan instead.
The consensus is a gradual correction, not a crash. S&P Global's base case is a slow adjustment through 2027 that could speed up in investor heavy apartment segments as deliveries peak. Emaar's chairman expects 5 to 10 per cent off prices across the sector. Nobody serious is forecasting 2008 or 2014, when prices fell 30 to 50 per cent: developers are better capitalised, escrow rules protect buyer deposits, cash buyers dominate, and the population is growing rather than shrinking. What the market is doing is giving back part of a 2025 that ran ahead of itself.
My own view, for what it is worth, is that 2026 and 2027 will be remembered as the entry window of this cycle in the right districts and the wrong years to have bought a generic tower in the wrong ones. The difference will be the building, the developer and the price per square foot against the area's rents, which is the whole of what this site is about.
Emaar South
On the edge of the championship golf course, five minutes from Al Maktoum International. A long handover and a low entry point for an Emaar address.
Business Bay
A Business Bay tower with Burj Khalifa and canal views, and one of the shortest waits for handover on this site.
Sobha Sanctuary
One and two bedroom apartments in Sobha's woodland enclave. The lowest priced way onto a Sobha address.
Haven by Aldar
Aldar's cheapest Dubai entry, from the strongest rated developer selling in the city.
Dubai Maritime City
Sea view apartments branded with Chelsea Football Club, with 5% to secure. A name international buyers and tenants recognise.
Dubai Islands
Boutique beachfront residences by Ellington on Dubai Islands, for buyers who want design and a waterfront address.
No. Sales in the third quarter of 2026 were down 47 per cent by value against a record 2025, but prices are only 1.7 to 3 per cent below a year ago on the main indices and 5 to 15 per cent off the peak in the softest segments. Forecasters expect a gradual correction, not the 30 to 50 per cent falls of 2008 or 2014.
For the right building, yes. It is the first buyer's market since 2020, with discounts, longer payment plans and negotiable resale prices. It is a bad time to buy a generic tower in an oversupplied district. The gap between the two has never been wider.
About 72 per cent of transactions and 65 per cent of value in the third quarter of 2026, down from 76 per cent in the spring. Ready sales are growing as completed stock from the 2022 and 2023 launches reaches the market.
On new leases, yes, particularly in mid market apartment districts with heavy completions. Renewals are capped by the RERA rent index and have barely moved. Citywide rents were down about 1 per cent over three months to May 2026 after rising about 10 per cent a year in 2024 and 2025.
About 55,600 completions are expected in 2026 and more than 60,000 in 2027, with around 180,000 across 2026 to 2028 on Moody's estimate. Historically less than half of what is scheduled arrives on time.
About 7.2 per cent gross for apartments and 5.0 per cent gross for villas and townhouses on Cavendish Maxwell's first quarter 2026 figures. Net yields, after service charges and voids, are roughly a fifth lower.
Sources: Cavendish Maxwell, Dubai residential market reports, Q1 to Q3 2026; ValuStrat, Dubai price index, March and August 2026; W Capital and Harbor, Q3 2026 transaction reports from Dubai Land Department data; Cushman and Wakefield Core, supply outlook 2026; S&P Global Ratings, UAE real estate, September 2026; Projectory Research, September 2026 DLD summary; Bayut and Property Finder area indices, September and October 2026; Reuters, 21 September 2026 (Mohamed Alabbar). Exchange rate AED 4.863 to the pound. Updated 22 October 2026.
Talk to me directly
Pick a time that suits you. We will go through your budget, your goals and what is available now. No cost and no obligation.
Keep reading
AED 1,636 per sq ft citywide, what that is in pounds, prices by area and type, five years of growth and where prices are heading.
Read moreEvery fee on a Dubai purchase itemised, and the tax position for an overseas owner.
Read moreDowntown, Palm Jumeirah, the Marina, Business Bay, Creek Harbour, Dubai Hills, Dubai South and JVC, with gross yields for each.
Read more